As the year begins to wind down, it’s natural to look ahead to the holidays and prepare for the coming year. It’s also an ideal time to review your financial situation and determine whether there are year-end tax opportunities worth considering before December comes to a close.
While some tax strategies must be implemented before year-end, many people don’t begin reviewing their options until the last few weeks of December. Starting earlier provides more time to gather information, consult with financial and tax professionals, and make thoughtful decisions rather than rushing to meet deadlines.
Every tax situation is unique, but a proactive review may help identify opportunities that align with your financial goals.
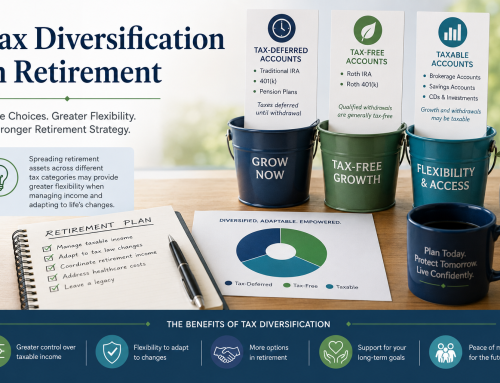
Review Retirement Plan Contributions
Retirement account contributions often play an important role in year-end tax planning.
Consider reviewing contributions to:
- Employer-sponsored retirement plans
- Traditional IRAs
- Roth IRAs
- SEP IRAs or SIMPLE IRAs, if applicable
If you are contributing through payroll deductions, increasing your contribution rate before year-end may allow you to make additional progress toward your retirement savings goals. Reviewing contribution limits early also gives you time to determine whether adjustments fit within your budget.
Evaluate Investment Activity
Investment activity throughout the year may have tax implications that are worth reviewing before December.
Questions to consider include:
- Have I realized capital gains this year?
- Have any investments declined in value?
- Does my portfolio still align with my long-term objectives?
- Should I discuss tax-loss harvesting with my advisor?
Tax-loss harvesting may be appropriate in certain situations, but it is subject to IRS rules and should be evaluated within the context of your overall financial plan.
Consider Charitable Giving
For many individuals and families, charitable giving is part of both their financial planning and personal values.
Planning gifts before year-end provides time to evaluate available strategies, which may include:
- Cash contributions
- Gifts of appreciated securities
- donor-advised funds
- qualified charitable distributions (QCDs) for eligible individuals
The most appropriate approach depends on your financial circumstances and philanthropic goals.
Review Required Minimum Distributions
If you are subject to required minimum distributions (RMDs)1, confirm that distribution requirements have been addressed before applicable deadlines.
Waiting until the end of December may increase the risk of administrative delays or missed deadlines, particularly if financial institutions experience higher processing volumes.
Reviewing RMD obligations early can also provide additional time to coordinate distributions with other aspects of your tax planning strategy.
Review Flexible Spending Account Balances
If you participate in a flexible spending account (FSA)2, now is a good time to review your remaining balance.
Depending on your employer’s plan provisions, unused funds may be subject to forfeiture or limited carryover rules.
Understanding your plan’s deadlines can help you determine whether eligible healthcare expenses should be scheduled before year-end.
Verify Estimated Tax Payments
Individuals who are self-employed, receive significant investment income, or have other sources of income outside of regular payroll withholding may benefit from reviewing estimated tax payments.
Comparing estimated payments with projected income may help identify whether adjustments should be discussed with a qualified tax professional before the year concludes.
Organize Tax Documents
Preparing for tax season becomes much easier when documents are organized before January arrives.
Consider gathering:
- Investment statements
- Charitable contribution receipts
- Healthcare expense records
- Retirement account information
- Business expense documentation, if applicable
Organizing records throughout the year can simplify tax preparation and reduce the likelihood of overlooking important information.
Avoid Last-Minute Decisions
One of the most valuable aspects of early year-end planning is having time to make thoughtful decisions.
Waiting until the final days of December may limit available options and create unnecessary stress. Beginning the review process several weeks earlier allows time to evaluate strategies, ask questions, and coordinate with financial and tax professionals when appropriate.
Planning Ahead for Year-End
Year-end tax planning is not about finding one strategy that fits everyone. Instead, it involves reviewing your financial situation, understanding available opportunities, and determining which actions align with your goals.
By evaluating retirement contributions, charitable giving, investment activity, required minimum distributions, and other tax-related considerations before December, you can approach year-end with greater organization and a clearer understanding of the decisions that remain available.
Sources:
- [1] https://www.investopedia.com/terms/r/requiredminimumdistribution.asp
- [2] https://www.investopedia.com/articles/personal-finance/060215/how-flexible-spending-accounts-work.asp