Throughout much of your working years, financial planning is often centered on building assets. Saving consistently, contributing to retirement accounts, and growing investments are common priorities as you prepare for the future.
As retirement approaches, however, the focus often begins to shift. Instead of asking, “How much have I accumulated?,” many retirees begin asking, “How will these assets provide income throughout retirement?”
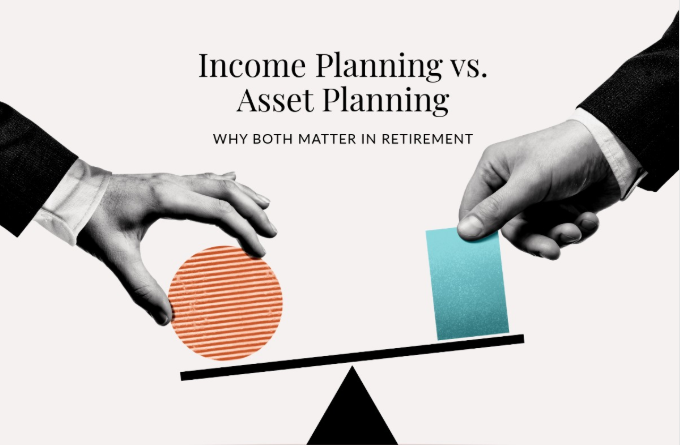
While asset planning and income planning are closely connected, they serve different purposes. Understanding how they work together can help create a more comprehensive retirement strategy that adapts to changing needs over time.
What Is Asset Planning?
Asset planning focuses on building, managing, and preserving financial resources.
This process often includes:
- Saving for retirement
- Building investment portfolios
- Managing risk through diversification
- Reviewing asset allocation1
- Planning for long-term growth
During the accumulation years, success is often measured by progress toward savings goals and the growth of investment accounts.
Asset planning provides the foundation upon which retirement income planning is built.
What Is Income Planning?
Income planning focuses on how financial resources may be used to support spending throughout retirement.
Instead of concentrating primarily on account balances, income planning asks questions such as:
- Where will retirement income come from?
- How much income may be needed each month?
- Which accounts should be used first?
- How might taxes affect withdrawals?
- How can income needs change over time?
The answers often involve coordinating multiple income sources rather than relying on a single account.
Common Sources of Retirement Income
Most retirees receive income from several different sources.
These may include:
- Social Security2 benefits
- Employer retirement plans
- Individual retirement accounts (IRAs)
- Taxable investment accounts
- Pension income, when available
- Part-time employment or consulting income
Understanding when and how these income sources may be used is an important part of retirement planning.
Why Asset Values Don’t Tell the Entire Story
Two individuals with similar investment balances may have very different retirement experiences.
Factors that influence retirement income include:
- Annual spending needs
- Healthcare expenses
- Taxes
- Investment allocation
- Longevity
- Inflation
- Withdrawal strategies
A portfolio balance provides useful information, but it does not automatically indicate how long assets may last or how income should be structured.
Looking beyond account values helps create a more complete picture.
Planning for Different Stages of Retirement
Retirement spending often changes over time.
Many retirees experience three broad phases:
- Early retirement, when travel and recreational spending may be higher.
- Middle retirement, when spending often becomes more consistent.
- Later retirement, when healthcare and caregiving expenses may become larger considerations.
Income planning can help prepare for these changing spending patterns by recognizing that retirement is not a single financial stage.
The Importance of Tax Planning
Taxes can influence retirement income just as much as investment performance.
Withdrawals from different account types may receive different tax treatment depending on applicable laws and individual circumstances.
A retirement income strategy may involve coordinating withdrawals from:
- Tax-deferred accounts
- Tax-free accounts
- Taxable investment accounts
Considering taxes alongside income planning may provide additional flexibility throughout retirement.
Building Flexibility Into Your Plan
No one can predict exactly what retirement will look like.
Markets fluctuate. Spending needs change. Tax laws evolve. Healthcare costs may increase.
Rather than creating a rigid strategy, many retirees benefit from a plan that can be reviewed and adjusted over time.
Regular evaluations allow individuals to respond thoughtfully to changing circumstances while keeping long-term goals in focus.
Questions to Consider
As you think about retirement planning, consider asking yourself:
- Have I focused primarily on accumulating assets?
- Do I have a strategy for generating retirement income?
- How will my spending change throughout retirement?
- Have I considered the tax impact of withdrawals?
- When was the last time I reviewed my retirement income plan?
These questions can help identify areas that deserve additional attention.
Bringing Your Retirement Strategy Together
Asset planning and income planning are not competing strategies. They are complementary parts of a comprehensive retirement plan.
Building assets during your working years provides the resources that support retirement. Income planning helps determine how those resources may be used to meet spending needs over time.
By considering both accumulation and distribution strategies, individuals can develop a more complete understanding of retirement planning and make informed decisions as their financial needs evolve.
Sources:
- [1] https://www.nerdwallet.com/investing/learn/what-is-asset-allocation
- [2] https://www.ssa.gov/